Past Workshops

1st Workshop

CityU Workshop in Econometrics and Statistics
17 August 2019 · City University of Hong Kong

Venue
8th Floor, Lau Ming Wai Academic Building, City University of Hong Kong

Keynote Speech

Jean-Marie Dufour

Jean-Marie Dufour

McGill University

Keynote Speech
Simple Estimators for Higher-order Stochastic Volatility Models and Forecasting

Jean-Marie Dufour is Professor of Economics and holds the William Dow Chair of Political Economy at McGill University. His research develops statistical methods for analysing economic and financial data, linking econometric theory with questions in macroeconomics and finance. His training spans mathematics at McGill, statistics at the Université de Montréal and economics at the University of Chicago. Dufour is a Fellow of the Econometric Society, the Royal Society of Canada and the American Statistical Association. His research distinctions include the Killam Prize for Social Science, the Léon-Gérin Prize, the John Rae Prize for Outstanding Research and a Guggenheim Fellowship. He has also been appointed an Officer of the Order of Canada and of the National Order of Québec. His service to the profession includes the presidency of the Canadian Economics Association and leadership of the Canadian Econometric Study Group. These contributions reflect a career spanning econometrics, statistics and economic research.
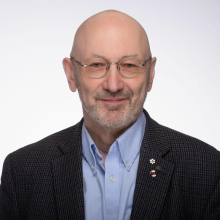
Official profile

Programme

17 August 2019 · All times are Hong Kong Time (UTC+8).

1st Workshop programme, 17 August 2019
TimeSpeaker / ItemPaper Title
9:00–9:15 a.m.Opening Speech · Frank ChenWelcome to Participants
Keynote · Chair: Alan Wan
9:15–10:00 a.m.Keynote · Jean-Marie DufourSimple Estimators for Higher-order Stochastic Volatility Models and Forecasting
10:00–10:30 a.m.BreakFirst coffee break
Session 1 · Chair: Xu Han
10:30–11:00 a.m.Xingbai XuLarge Sample Properties of Bayesian Estimation of Spatial Econometric Models
11:00–11:30 a.m.Kin Wai ChanEstimator of Asymptotic Covariance Matrix in Non-stationary Time Series
11:30 a.m.–12:00 p.m.Lilun DuDynamic Tracking and Screening in Massive Datastreams
12:00–2:00 p.m.BreakLunch
Session 2 · Chair: Gavin Feng
2:00–2:30 p.m.Liyuan CuiA Machine Learning Approach to Estimating Large Positive Definite Covariance Matrix of High Frequency Data
2:30–3:00 p.m.David RapachThe Rise and Fall of the Carry Trade: Links to Currency Return Predictability
3:00–3:30 p.m.Zhonghao FuEstimation and Testing Distributional Changes via Characteristic Function
3:30–4:00 p.m.BreakSecond coffee break
Session 3 · Chair: Alan Wan
4:00–4:30 p.m.Yuying SunModel Averaging for Interval-valued Data
4:30–5:00 p.m.Jun LiaoFrequentist Model Averaging for the Nonparametric Additive Model
5:00–5:30 p.m.Wenhao WangA Jackknife Model Averaging Analysis of RMB Misalignment Estimates
5:30–5:35 p.m.Closing Remarks

Co-Chairs: Gavin Feng and Alan Wan.